A furniture loan is usually a personal loan used to buy furniture. You borrow a set amount, buy the sofa, bed or dining table, then repay it with interest and fees over a fixed term. Several lenders offer this kind of loan, and their terms differ, so comparing before you apply is the step that matters most. At AFH Finance we are a broker, not a lender. We compare personal loan options from a panel of 40+ lenders Australia wide. There is No cost to check your options, because we are paid by lenders and a broker fee may be added to the loan, always explained in writing before anything proceeds.
See your options from our panel of 40+ lenders
Soft enquiry, no credit score impact. No cost to check your options.
Compare my optionsThis is general information only, not personal advice. Your situation decides which option suits you, so it is worth talking to a broker about it.
AFH Finance
Compare options for planned purchases
AFH Finance compares personal loan options from 40+ lenders, with a soft enquiry that has no impact on your credit score.
TL;DR
- Furniture finance is not one product. It can be a personal loan, a store payment plan, a buy now pay later account or a No Interest Loan for people on low incomes.
- A personal loan for furniture is repaid with interest over a set term, usually one to seven years, according to Moneysmart.
- Compare the total you will repay, not just the weekly or monthly amount. Fees and loan term change the final cost.
- Rates are set by the lender based on the borrower’s situation, so two people can be offered different terms.
- A broker can compare lenders that may suit you. Soft enquiry, no credit score impact.
Table of Contents
- What a furniture loan actually is
- The main ways Australians finance furniture
- How a personal loan for furniture works
- What to check before you choose
- Why compare through a broker
- For ABN holders and sole traders
- Compare furniture finance with AFH Finance
- Our view on financing furniture
- FAQ
- Sources
What a furniture loan actually is
Lenders rarely sell a product called a furniture loan. The phrase is how people describe borrowing to furnish a home. A new rental, a first home, a renovation or a replacement lounge room can each lead to a purchase of several thousand dollars at once.
Most often the money comes from a personal loan. Moneysmart, the consumer site run by ASIC (the Australian Securities and Investments Commission), explains that a personal loan gives you money for things like a car, holiday or home improvement. You repay it with interest over a set term, usually one to seven years.
Because the money lands in your account, you choose where to shop. You can buy from a major retailer, a local maker, a showroom or a private seller. That flexibility is a main reason people prefer a personal loan to a plan tied to one store.
What the money can cover
Planned purchases are the natural fit. For a home, that can mean:
- A bedroom suite, mattress and bedside tables
- A lounge, sofa and coffee table
- Dining table and chairs
- A home office desk and chair
- Outdoor settings for a new deck or patio
If you are renovating, furniture often sits alongside other costs. Our personal loans cover renovations, travel, weddings and other planned purchases, so one loan can be compared for the whole project instead of several small ones.
The main ways Australians finance furniture
Before choosing, it helps to see the field. ASIC’s credit factsheet lists personal loans, household goods rentals, rent to buy, store deals with no interest and buy now pay later as different forms of credit. They work differently and cost differently.
| Option | How it works | What to watch |
|---|---|---|
| Personal loan | Lump sum repaid over a set term with interest and fees | Total repayments, fees, loan term |
| Store payment plan | Pay for the item in instalments through the retailer | Account fees, minimum payments, what happens when the offer period ends |
| Buy now pay later | Split a purchase into scheduled payments | Late fees can add up quickly, according to the ASIC factsheet |
| Credit card | Put the purchase on a card and repay over time | Card interest, which NSW Fair Trading says is often higher than personal loan interest |
| No Interest Loan | Community loan for essential goods, for people on low incomes | Strict eligibility and a limit of generally $2,000 |
The table is a map, not a ranking. Which row suits you depends on the amount, your income and how you want to repay.
Store plans and buy now pay later
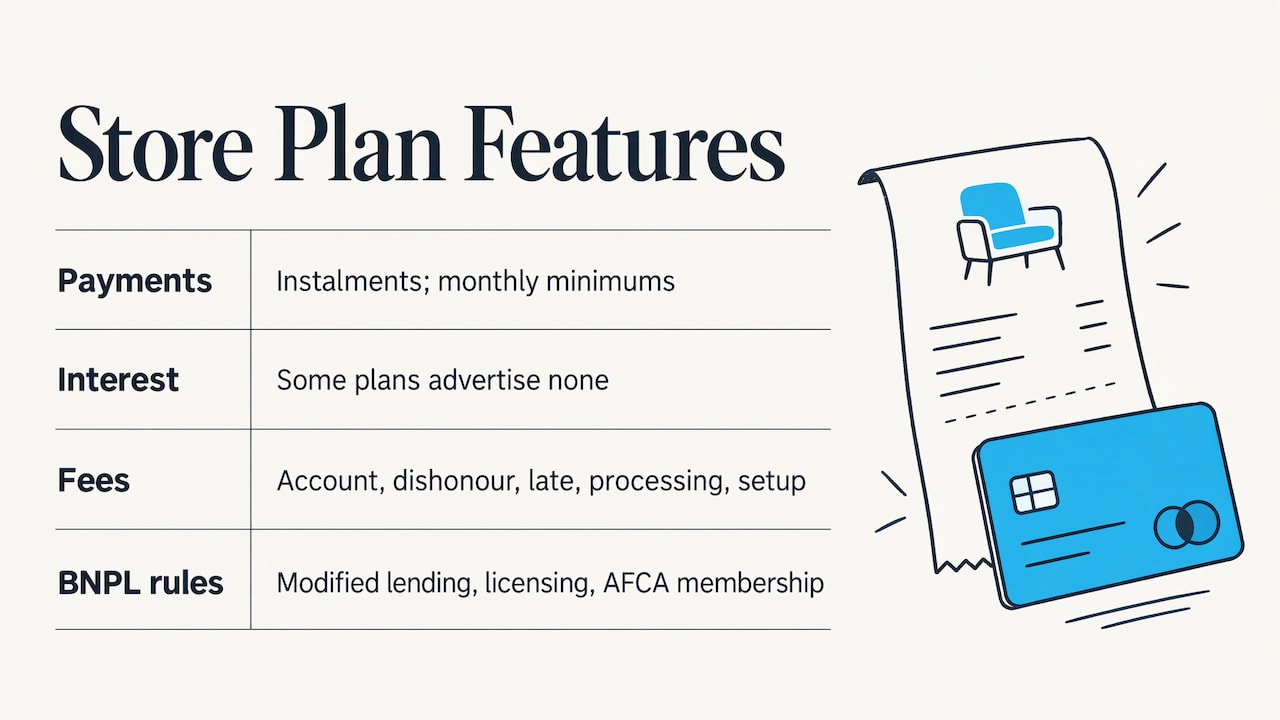
Store plans and buy now pay later accounts let you pay in instalments, and some advertise no interest. NSW Fair Trading notes that this kind of finance can still carry monthly account, dishonour, late, processing or establishment fees, and normally requires minimum monthly payments. Read the contract for those charges, and find out what applies if you miss a payment.
The rules around buy now pay later have also tightened. The ACCC noted in a June 2025 paper that amendments brought providers under modified responsible lending obligations, Australian credit licensing requirements and membership of the Australian Financial Complaints Authority (AFCA).
No Interest Loans
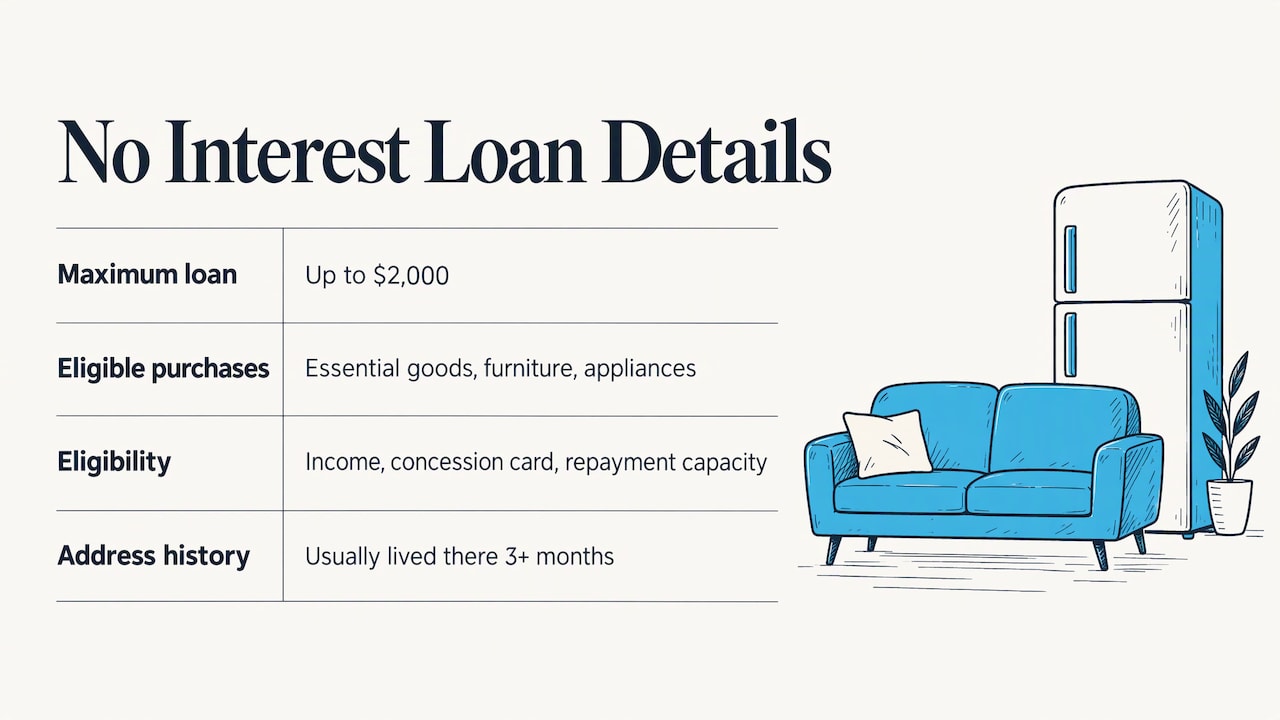
There is also a community scheme worth knowing about. Moneysmart says a No Interest Loan generally allows up to $2,000 for essential goods and services, including furniture and appliances. Eligibility depends on factors such as income, holding a concession card, repayment capacity and usually having lived at your address for at least three months. It is designed for people on low incomes, so most employed Australians and ABN holders planning a larger purchase look at the other options above.
How a personal loan for furniture works
The mechanics are simple, and knowing them makes comparison easier.
- Amount. You decide what the purchase will cost, including delivery and any extras.
- Term. You choose a repayment period. Moneysmart says personal loans usually run one to seven years.
- Rate and fees. The lender sets the interest rate based on your situation. Application, establishment and ongoing fees may apply.
- Repayments. You repay on a regular schedule until the loan ends.
- Total cost. The gap between what you borrowed and what you repay overall is the cost of the credit.
Two loans for the same amount can cost very different totals. A longer term lowers each repayment but usually means more interest overall. A shorter term does the reverse. Neither is automatically right. It depends on your budget, and that is a conversation to have with a broker about your own circumstances.
Secured and unsecured
Some personal loans are secured against an asset, such as a car. Others are unsecured, which means no asset is pledged. Our guide to unsecured personal loans in Australia explains how they work and what lenders look at.
What to check before you choose
Furniture feels like a small purchase until the loan terms arrive. ASIC’s credit factsheet says credit generally costs more than cash, because you repay the principal plus interest and fees, and it recommends checking the total repayment including all extra charges.
Moneysmart’s personal loan guide lists the items to compare. Use it as a checklist:
- Application or establishment fees. Charged when the loan starts.
- Ongoing administration fees. Charged monthly or yearly.
- Missed payment fees and default interest. What it costs if a repayment is late.
- Early repayment fees. Whether paying the loan off sooner triggers a charge.
- Balloon payments. A large final payment that lowers the regular amounts but must be paid at the end.
- Loan term. How long you will be repaying, and what total that produces.
With two offers side by side, put the total repayment for each in one line. The lower weekly figure is not always the lower total.
Rates are personal
We do not publish rates, because they are set by the lender based on the borrower’s situation. Your income, employment, expenses and credit history all play a part. Any rate you see advertised is a starting point for some borrowers, not a promise for you. Check your own offer in writing before you sign.
Watch the number of applications
Moneysmart warns that applying for many loans can hurt your credit score. That is a reason to compare in one place rather than applying lender by lender. Checking your options with us is a soft enquiry, with no credit score impact.
Why compare through a broker
A retailer shows you its own finance. A single lender shows you its own loan. A broker looks across a panel. We are paid by lenders, and a broker fee may be added to your loan, always explained in writing before anything proceeds.
What that means in practice:
- A real broker, not a call centre, compares our panel of 40+ lenders for you.
- You start online with a short set of questions and see indicative repayments.
- A broker then calls you to confirm the options that may suit your situation.
- Fees are explained in writing before you go ahead.
That structure suits busy people. You fill in a few questions once, instead of reading terms from a dozen lenders and applying to several.
Steps to compare furniture finance
- Price the purchase. Add up the items, delivery and assembly so the loan reflects the whole cost.
- Decide a repayment term you are comfortable with. Shorter terms cost less interest overall, longer ones lower each repayment.
- Check your options. Answer our short online questions and see indicative repayments. No cost to check your options. Soft enquiry, no credit score impact.
- Talk to a broker. A broker confirms the lenders that may suit you and walks through fees and documents.
- Read the written fee explanation. Compare total repayments, fees and any early repayment charge.
- Proceed only if it fits your budget. The decision stays with you.
For ABN holders and sole traders
If you run a business, furniture can be a mix of personal and work spending. A sole trader setting up a home studio, for example, may be weighing a personal loan against other finance. Because we work with employed Australians and ABN holders, a broker can talk through which type of loan may suit your situation. For business purchases, see our business loans and equipment finance page, and our guide to equipment business loans for how that kind of finance works.
Compare furniture finance with AFH Finance
If you are planning a furniture purchase, our personal loans page is the place to start. We are a broker with a panel of 40+ lenders, serving borrowers Australia wide, with 750+ borrowers helped and a 5.0 rating on Google from 63 reviews. You answer a few questions, see indicative repayments and a broker calls you about the options that may suit you.
No cost to check your options. Soft enquiry, no credit score impact. AFH Finance is paid by lenders, and a broker fee may be added to the loan, always explained in writing before anything proceeds.
Our view on financing furniture
Furniture is one of the purchases people most often finance without much thought, because it feels like an everyday expense. A few thousand dollars over several years is still a real commitment, so it deserves the same comparison as a car.
We start with the total repayment, not the headline weekly figure. When we talk to borrowers, we ask what the purchase is, what repayment term feels comfortable, and how the fees add up, then we explain those fees in writing before anything proceeds.
We are a broker, not a lender. That lets a real broker compare a panel of 40+ lenders Australia wide and show options that may suit the borrower, rather than offering one product. Rates are set by the lender based on your situation, which is why we do not publish them.
If you are buying furniture, renovating or planning another major purchase, talk to a broker about your situation. Checking your options is a soft enquiry with no credit score impact.
AFH Finance
FAQ
Is it okay to finance furniture?
For many people it can be a workable way to spread the cost of a planned purchase, provided the repayments fit the budget. Credit generally costs more than paying cash, because you repay the amount borrowed plus interest and fees. Compare total repayments before deciding, and talk to a broker about your situation.
Can I use a personal loan for furniture?
Yes. Moneysmart describes personal loans as money for purposes such as a car, holiday or home improvement, and furniture is a common planned purchase. Lenders set their own terms, so the interest rate, fees and loan term depend on the lender and on your situation.
What fees should I look for on furniture finance?
Check application or establishment fees, ongoing administration fees, missed payment fees and default interest, early repayment fees and any balloon payment. NSW Fair Trading also notes that store plans with no interest can still carry account, late or processing fees. Add everything up and compare the total repayment.
Does checking my options affect my credit score?
With us, checking your options is a soft enquiry, no credit score impact. Moneysmart does warn that applying for many loans can hurt a credit score, so comparing through one broker can be easier than applying to several lenders yourself.
Is there a cost to compare furniture loans with AFH Finance?
No cost to check your options. AFH Finance is paid by lenders, and a broker fee may be added to the loan. We always explain any fee in writing before anything proceeds.
Sources
- Personal loans, Moneysmart
- No Interest Loans, Moneysmart
- Credit factsheet, Moneysmart and ASIC
- Understanding personal loans and the alternatives, NSW Fair Trading
- ACCC consultation paper, June 2025
Recommended
- Unsecured Personal Loans in Australia: How They Work
- Business Asset Finance in Australia: How It Works
See your options from our panel of 40+ lenders
Soft enquiry, no credit score impact. No cost to check your options.
Compare my optionsGeneral information only. This article doesn't consider your objectives, financial situation or needs, and isn't a credit offer. Lending criteria, fees and charges apply. We're paid by lenders, and a broker fee may be added to your loan. AFH Finance Pty Ltd, Credit Representative 548852 of Access Lending Group Pty Ltd, ACL 531308.